How to Calculate Monthly Loan Payments: Formula & Examples
Taking out a loan is a significant financial commitment. Whether you are financing a car, borrowing money for a personal expense, or planning a major purchase, knowing your monthly payment can help you understand how the loan will fit into your budget.
The good news is that you can estimate monthly loan payments using a straightforward mathematical formula or an online loan payment calculator.
Your monthly payment generally depends on three main factors: the amount you borrow, the interest rate, and the repayment period. Additional charges and the specific terms of your loan can also affect the amount you ultimately pay.
In this guide, you will learn how to calculate monthly loan payments, understand the formula, work through a practical example, and compare different loan options before making a borrowing decision.
What Is a Monthly Loan Payment?
A monthly loan payment is the amount you pay to a lender each month according to your loan agreement.
For a typical fixed-rate installment loan, each payment covers two components:
- Principal: The portion that repays the money you originally borrowed.
- Interest: The cost charged by the lender for lending you money.
With a standard amortizing loan, your payment is usually the same each month when the interest rate and repayment terms remain unchanged. However, the portions allocated to principal and interest change over time.
Some loans may also involve fees, insurance, taxes, or other charges. These are not necessarily included in a basic monthly loan payment calculation.
What Information Do You Need?
Before calculating a monthly loan payment, gather the following information.
1. Loan amount
This is the principal you intend to borrow. For example, if you borrow $15,000, your starting principal is $15,000.
2. Annual interest rate
The interest rate determines how much interest is charged on the outstanding loan balance. For the example below, we will use an annual interest rate of 8%.
Make sure you understand whether the quoted rate is a nominal annual rate, an effective annual rate, or an APR that includes certain borrowing costs. These measures are not always interchangeable.
3. Loan term
The loan term is the period over which you will repay the money.
For example, a three-year loan with monthly payments has:
3 × 12 = 36 monthly payments.
4. Additional fees
Depending on the loan, you may need to consider origination fees, arrangement fees, insurance, or other charges. A standard payment formula does not automatically include every cost associated with borrowing.
Monthly Loan Payment Formula
For a standard fixed-rate amortizing loan with equal monthly payments, use the following formula:
M = P × r × (1 + r)ⁿ ÷ [(1 + r)ⁿ − 1]
Where:
- M = monthly loan payment
- P = principal loan amount
- r = monthly interest rate expressed as a decimal
- n = total number of monthly payments
To calculate the monthly interest rate from a nominal annual rate, divide the annual rate by 12 and convert the percentage into a decimal.
For example, if the annual interest rate is 8%:
Monthly interest rate = 0.08 ÷ 12 = 0.0066667
For a three-year loan:
Number of payments = 3 × 12 = 36
You can then substitute the principal, monthly rate, and number of payments into the formula.
Important: This formula assumes a positive fixed interest rate and regular monthly payments. For a zero-interest loan, the monthly payment is simply the principal divided by the number of payments.
Worked Example: Calculate a Monthly Loan Payment
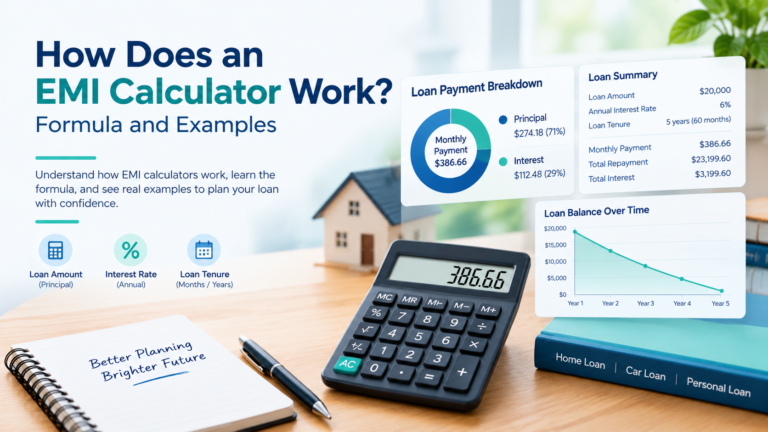
Suppose you want to borrow $15,000 to purchase a car or cover another major expense.
Your loan details are:
| Loan detail | Value |
|---|---|
| Principal | $15,000 |
| Annual interest rate | 8% |
| Loan term | 3 years |
| Number of payments | 36 |
| Monthly interest rate | 0.6667% |
| Estimated monthly payment | $470.05 |
| Estimated total repayment | $16,921.64 |
| Estimated total interest | $1,921.64 |
Figures are rounded to the nearest cent and assume a fixed nominal annual rate of 8%, monthly payments, and no additional fees.
Step 1: Convert the annual interest rate
Divide the annual rate by 12:
8% ÷ 12 = approximately 0.6667% per month.
In decimal form, the monthly rate is approximately 0.0066667.
Step 2: Calculate the total number of payments
Multiply the number of years by 12:
3 × 12 = 36 payments.
Step 3: Apply the monthly payment formula
Using a principal of $15,000, a monthly rate of approximately 0.0066667, and 36 payments gives an estimated monthly payment of $470.05.
Step 4: Calculate the total repayment
Multiply the unrounded monthly payment by the number of payments.
Total repayment = Monthly payment × Number of payments
The estimated total repayment is approximately $16,921.64.
Step 5: Calculate the total interest
Subtract the original principal from the total repayment.
Total interest = Total repayment − Principal
$16,921.64 − $15,000 = approximately $1,921.64.
This example shows why it is important to consider the total cost of borrowing rather than looking only at the monthly payment.
How Does the Loan Term Affect Monthly Payments?
The repayment period can make a substantial difference to your monthly budget.
Generally, spreading the same loan over a longer period reduces the monthly payment. However, because interest may be charged for more months, the total interest cost can increase.
A shorter term generally produces higher monthly payments but may reduce the total interest paid.
For example, consider a fixed-rate loan with the same principal and interest rate:
- A shorter term means you repay the principal more quickly.
- A longer term spreads repayment over more months.
- The best option depends on both affordability and the overall cost.
Before choosing a longer term just to lower your monthly payment, compare the total repayment amount and check whether the loan allows early repayment without penalties.
How Does the Interest Rate Affect Monthly Payments?
The interest rate determines the cost of borrowing, assuming other loan details remain the same.
A higher interest rate generally results in a higher monthly payment and a greater total interest expense. A lower rate generally reduces both.
When comparing loan offers, make sure the rates are being presented on a comparable basis.
For example, a lender might advertise a nominal interest rate, while another highlights an annual percentage rate or APR that includes certain borrowing costs. The exact definition and calculation of these rates vary by country and product.
Compare the loan’s fees, repayment period, rate structure, and total cost—not just the advertised rate.
How to Calculate Monthly Payments Without a Calculator
You can calculate the payment manually if you know the principal, monthly interest rate, and number of payments.
Follow these steps:
- Identify the principal amount.
- Convert the annual nominal interest rate to a monthly decimal rate.
- Multiply the loan term in years by 12 to find the number of payments.
- Apply the fixed-rate loan payment formula.
- Multiply the unrounded monthly payment by the number of payments to estimate the total repayment.
- Subtract the principal from the total repayment to estimate total interest.
Although the formula is useful for understanding the mathematics, manual calculations can be time-consuming. An online calculator can make it easier to compare several loan scenarios.
Use TibCal’s Monthly Loan Payment Calculator
You can use TibCal’s finance calculators to estimate payments and explore different borrowing scenarios.
To calculate a monthly payment:
- Open the relevant loan payment calculator on TibCal.
- Enter the amount you want to borrow.
- Enter the annual interest rate.
- Select the repayment term.
- Calculate the estimated payment.
- Review the total repayment and interest, if displayed.
- Change the interest rate or loan term to compare alternatives.
Try it now: Loan Payment Calculator.
If you are comparing a mortgage or home loan, use the relevant mortgage calculator instead. Mortgage payments may involve additional costs that are not included in a basic loan payment calculation.
Monthly Loan Payment vs. Total Loan Cost
Your monthly payment tells you how much you may need to pay regularly, but it does not tell the entire story.
Consider these three figures when evaluating a loan:
Monthly payment: The scheduled payment amount.
Total repayment: The sum of scheduled payments over the full term.
Total interest: The amount paid above the original principal, assuming the total repayment figure includes only principal and interest.
A loan with a lower monthly payment may have a longer term and a higher total cost. A loan with a higher monthly payment may cost less overall if it is repaid more quickly.
Fees, insurance, taxes, and other charges can also change the comparison. Review the full terms before choosing a loan.
Common Mistakes When Calculating Loan Payments
Using the annual rate as the monthly rate
For a nominal annual rate with monthly payments, you generally need to divide the annual rate by 12 and express it as a decimal. Entering 8 instead of 0.08, for example, produces an incorrect calculation.
Entering the wrong loan term
A three-year loan with monthly payments has 36 scheduled payments. Always check whether the calculator asks for months or years.
Ignoring fees and additional costs
A basic loan formula may exclude arrangement fees, origination fees, insurance, or other charges. Check whether these costs are included in the loan amount or charged separately.
Assuming every loan has a fixed rate
A variable-rate loan may become more expensive or less expensive as its rate changes. A calculation based on today’s rate cannot guarantee future payments for a variable-rate loan.
Choosing a loan based only on affordability
A payment may fit your monthly budget while still making the loan expensive overall. Consider total interest, other financial commitments, emergency savings, and the flexibility of the loan terms.
Frequently Asked Questions
How do I calculate my monthly loan payment?
For a standard fixed-rate amortizing loan, use the principal, monthly interest rate, and total number of monthly payments in the loan payment formula. An online loan calculator can perform the calculation for you.
What is the formula for monthly loan payments?
The formula is M = P × r × (1 + r)ⁿ ÷ [(1 + r)ⁿ − 1], where M is the monthly payment, P is the principal, r is the monthly interest rate as a decimal, and n is the total number of monthly payments.
Does a longer loan term lower the monthly payment?
Generally, yes. A longer term spreads repayment over more months, which usually reduces the required monthly payment. However, total interest may increase.
How can I calculate the total interest on a loan?
For a standard loan with equal payments, subtract the original principal from the total scheduled repayment. This assumes the total repayment includes only principal and interest, with no additional charges.
Is APR the same as the interest rate?
Not necessarily. The nominal interest rate describes the rate used to calculate interest under the loan’s terms. APR is a broader borrowing-cost measure that may include certain fees. Definitions and disclosure rules vary between countries and loan types.
Can I calculate a loan with no interest?
Yes. For a zero-interest loan with equal monthly payments, divide the principal by the number of payments. For example, $6,000 repaid over 12 months would require payments of $500 per month, before any additional fees.
Does the monthly payment include taxes and insurance?
Not always. A basic loan calculator generally estimates principal and interest. Some mortgage and vehicle financing arrangements may involve additional costs that need to be calculated separately.
Can I repay my loan early?
That depends on the loan agreement and local rules. Early repayment may reduce future interest, but some loans have prepayment or early-settlement charges. Check the lender’s conditions before making extra payments.
Final Thoughts
Calculating monthly loan payments helps you understand how much borrowing may cost and whether a repayment schedule fits your budget.
Start with the principal, interest rate, and loan term. Then compare the monthly payment, total repayment, and total interest across different scenarios. Remember to account for applicable fees and to check the lender’s actual terms before committing.
Use TibCal’s finance calculators to explore loan scenarios and make more informed comparisons.
Disclaimer: This article is for educational purposes only and does not constitute financial advice. The calculations are estimates based on stated assumptions and may exclude fees, insurance, taxes, and other charges. Actual loan terms and payments depend on the lender and loan agreement.